Slide 1
CONTECH MARKET REPORT
Construction Technology
Market Report 2026
Internal Briefing · November 2026
This presentation contains 11 slides covering the following content:
CONTECH MARKET REPORT
Construction Technology
Market Report 2026
Internal Briefing · November 2026
02 / 11
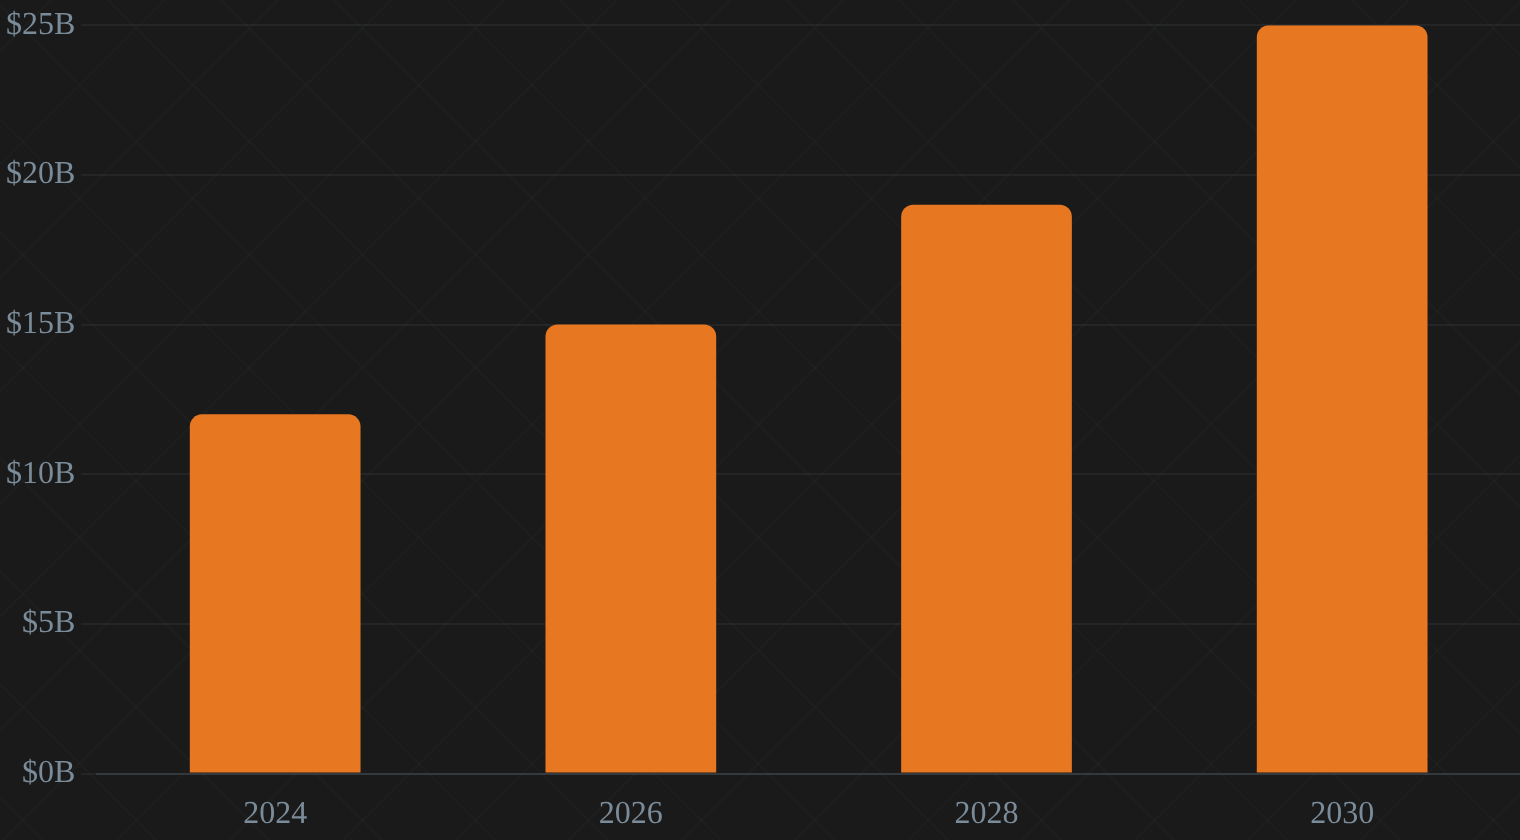
A $10–15B market growing at 12–18% CAGR
Global ConTech Market Size ($B)
$10–15B
Current market size
12–18%
CAGR through 2030
$25B+
Projected by 2030
03 / 11
Three forces are driving ConTech adoption
Labor Shortages
Aging workforce and skilled-labor gaps push firms toward automation and digital tools.
Sustainability Mandates
Carbon disclosure rules and green building standards require data-driven project tracking.
Digital Transformation
Cloud, mobile, and AI move construction from paper-based to platform-based workflows.
04 / 11
The market segments across tech type, phase, and end-user
BY TECH TYPE
Project Management
35%
BIM & Design
25%
Field & Site Tools
20%
Robotics & Automation
12%
Other
8%
BY PROJECT PHASE
Pre-construction
30%
Construction
40%
Operations & FM
30%
KEY INSIGHT
Construction-phase tools dominate spend, but O&M is the fastest-growing segment.
BY END-USER
General Contractors
45%
Owners / Developers
25%
Subcontractors
20%
AEC Firms
10%
05 / 11
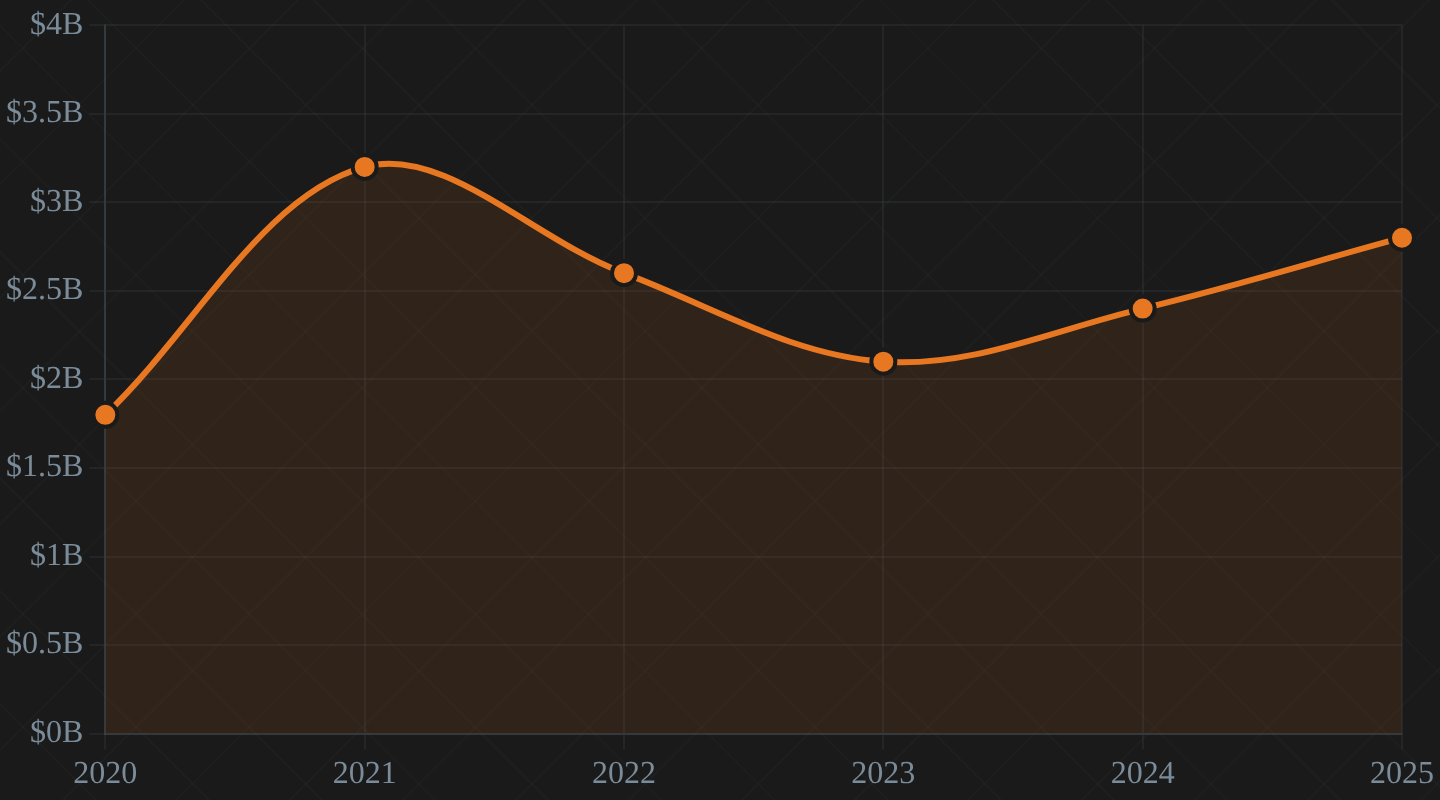
VC funding peaked in 2021, now refocusing on later-stage deals
ConTech VC Funding ($B)
$3.2B
Peak funding in 2021
~40%
Shift to later-stage deals since 2023
Procore, Autodesk, Trimble
Notable strategic acquirers
06 / 11 · ADOPTION BARRIERS
Three barriers slow ConTech adoption<br>across the value chain
BARRIER 01
Fragmentation
Thousands of small firms and siloed tools make standardization and integration difficult.
BARRIER 02
High Upfront Costs
Software licenses, hardware, and training require significant capital before ROI is visible.
BARRIER 03
Cultural Resistance
Industry traditionally relies on experience and relationships; digital workflows face skepticism.
07 / 11
Leaders, challengers, and niches across ConTech categories
PROJECT MANAGEMENT
Leaders
Procore, Autodesk Construction Cloud, Buildertrend
BIM & DESIGN
Leaders
Autodesk Revit, Nemetschek, Bentley Systems
FIELD & SITE
Challengers
OpenSpace, DroneDeploy, Fieldwire (Hilti)
AI ESTIMATING
Emerging
Togal.AI, Buildots, Disperse
ROBOTICS
Niche / Emerging
Built Robotics, Dusty Robotics, Canvas
DIGITAL TWINS
Growing
Autodesk Tandem, Bentley iTwin, Nvidia Omniverse
08 / 11
AI, robotics, and platform consolidation will shape the next 3–5 years
NEAR-TERM
2026–27
AI moves from pilot to production in estimating, scheduling, and risk detection.
MID-TERM
2027–29
Robotics and autonomous equipment scale from demos to deployed site operations.
LONG-TERM
2029–31
Platform consolidation creates end-to-end digital construction ecosystems.


09 / 11
Room to operate — now
Current whitespace: quick wins in project management and field tools
QUICK WIN
Project Management Platforms
SMB contractors still rely on spreadsheets. Lightweight, mobile-first PM tools have clear adoption runway.
~60% of contractors
lack dedicated project software
QUICK WIN
Field & Site Tools
Photo documentation, progress tracking, and safety reporting remain underserved for field teams.
Low penetration
in subcontractor segment


10 / 11
Room to operate — 1 year
Near-term openings in AI estimating, digital twins, and IoT integration
NEAR-TERM
AI Estimating
Automated quantity takeoff and bid preparation from drawings. Early adopters gaining margin advantage.
NEAR-TERM
Digital Twins
Live models linking BIM to real-time site data. Operations and FM use cases driving demand.
NEAR-TERM
IoT Integration
Sensor networks for equipment, safety, and environmental monitoring. Fragmented but growing fast.


11 / 11
Room to operate — 5 years
Long-term bets on autonomous construction and end-to-end platforms
LONG-TERM BET
Autonomous Construction
Self-operating equipment for excavation, layout, and finishing. Requires capital, patience, and safety validation.
5–7 year horizon
to commercial scale
LONG-TERM BET
End-to-End Platforms
Unified platforms spanning design, build, and operate. Winners will own the data layer across the lifecycle.
Consolidation play
M&A will accelerate
The window is open — but narrowing.

